
Blue Raider Adventure Park accounting is a topic associated with the ACTG 2110 Principles of Accounting I course at Middle Tennessee State University (MTSU). The case study introduces students to the accounting cycle through a fictional outdoor adventure business, helping them understand how business transactions become organized financial records.
The case follows Matt Lapinski, an MTSU student who wants to establish a small business that fits around his academic schedule. He plans to develop an adventure park on land owned by his grandfather near Murfreesboro, Tennessee. The proposed activities include canoeing, spelunking tours, an obstacle course, and ziplining.
Rather than focusing only on theory, the assignment places students in the role of helping Matt maintain accurate business accounts. They learn how to analyze transactions, record journal entries, post amounts to ledger accounts, prepare trial balances, make adjustments, and produce financial statements.
This guide explains the accounting principles behind the Blue Raider Adventure Park case study, walks through the main stages of the accounting cycle, and highlights common mistakes students should avoid. Exact numerical answers depend on the transactions, chart of accounts, and instructions in the original assignment packet.
What Is Blue Raider Adventure Park Accounting?
Blue Raider Adventure Park accounting refers to an educational accounting exercise that uses a fictional adventure park to demonstrate financial accounting principles. The supplied assignment pages identify the material as an ACTG 2110 accounting cycle packet covering Chapters 2–4 for Spring 2020.
The scenario begins with business development in August. The park opens to the public on September 1, and September 30 marks the end of its fiscal year. This short reporting period allows students to follow business activities from startup through month-end accounting procedures.
The case is designed to show that accounting principles apply to businesses of different sizes. A small adventure park and a large corporation may have different levels of complexity, but both need reliable records of assets, liabilities, revenue, expenses, and owners’ equity.
It is important to distinguish the educational scenario from an operating attraction. The supplied pages describe a classroom business case, not evidence that Blue Raider Adventure Park is a real commercial amusement park.
| 🔗 You may also like: |
| Startup Booted Financial Modeling: The Strategic Founder’s Guide |
| Growth Navigate Funding: A Guide to Business Funding & Growth |
Why Is the Case Study Important for Accounting Students?
Accounting students must understand more than the definitions of debits and credits. They also need to see how individual transactions affect a business’s financial position and how those transactions flow into formal reports.
The Blue Raider Adventure Park case provides a practical setting for developing these skills. Students work through connected accounting tasks, where an error in an early stage can affect the results of later stages.
For example, incorrectly recording an equipment purchase may lead to an incorrect ledger balance. That error can then affect the trial balance and balance sheet. Following the accounting cycle in order helps students identify problems before they spread through the records.
The case also introduces the importance of accounting deadlines. Because September 30 is the stated fiscal year-end, students must consider whether revenue and expenses have been recorded in the appropriate reporting period.
The Main Stages of the Blue Raider Adventure Park Accounting Cycle
The accounting cycle organizes financial information into a sequence of procedures. The supplied course material illustrates the following ten stages.
Analyze transactions
Identify the accounts affected and determine how each account changes.
Journalize transactions
Record transactions in the general journal using debits and credits.
Post to the ledger
Transfer journal amounts to their corresponding accounts.
Prepare the unadjusted trial balance
Compare total debit balances with total credit balances before adjustments.
Record adjusting entries
Update accounts for required accruals, deferrals, and depreciation.
Prepare the adjusted trial balance
Verify account balances after the adjusting entries have been posted.
Prepare financial statements
Use the adjusted balances to report profitability and financial position.
Close temporary accounts
Transfer revenue, expense, and withdrawal balances as required.
Prepare the post-closing trial balance
Check the remaining permanent accounts after closing.
Reverse selected entries, if applicable
Make optional reversing entries at the start of the next accounting period when appropriate.
The original packet explains that transaction analysis is introduced earlier in the textbook, while the assignment begins recording written accounting entries at the journalizing stage. Students should follow their instructor’s directions about which stages and schedules to complete.
Understanding Transactions in the Adventure Park Business
Before preparing journal entries, students must identify the financial effect of each business event. Matt’s business may involve startup investments, equipment purchases, operating expenses, and revenue from customer activities. However, the precise transactions and amounts must come from the original assignment.
The Accounting Equation
The foundation of financial accounting is the accounting equation:
Assets are resources controlled by a business, such as cash, equipment, and supplies. Liabilities represent obligations to other parties, such as unpaid supplier bills. Owner’s equity represents the owner’s residual interest in the business.
Every properly recorded transaction preserves this equation. For example, if an owner contributes cash to a sole proprietorship, cash increases and owner’s equity increases by the same amount.
If the business buys equipment with cash, one asset increases while another decreases. The transaction changes the composition of the assets but does not necessarily change total assets or create an immediate expense.
Debit and Credit Rules
Debits and credits are the two sides of the double-entry accounting system. Their effects depend on the type of account involved.
| Account type | Increase | Decrease |
|---|---|---|
| Assets | Debit | Credit |
| Liabilities | Credit | Debit |
| Owner’s equity | Credit | Debit |
| Revenue | Credit | Debit |
| Expenses | Debit | Credit |
| Owner’s withdrawals | Debit | Credit |
These rules help students analyze transactions before entering them into the journal. A debit does not automatically mean an increase, and a credit does not automatically mean a decrease.
For a detailed explanation of the initial accounting procedures, students can consult OpenStax’s Principles of Accounting textbook. It provides additional explanations of transaction analysis, journal entries, ledger posting, and trial balances.
| 🔗 You may also like: |
| Coyyn Digital Finance Innovation |
| Global Trader Programme: Financial & Business Growth |
How to Record Journal Entries
The general journal records transactions in chronological order. Each entry identifies the accounts affected, the debit and credit amounts, and any explanation required by the assignment.
Consider a hypothetical example in which an adventure park purchases equipment for $2,000 in cash. The amount is illustrative and is not an actual transaction from Matt’s assignment.
| Account | Debit | Credit |
|---|---|---|
| Equipment | $2,000 | — |
| Cash | — | $2,000 |
| Total | $2,000 | $2,000 |
Equipment is debited because the asset increases. Cash is credited because the asset decreases. Both sides equal $2,000, so the entry follows the double-entry principle.
Why Account Classification Matters
Not every payment should be recorded as an expense. Equipment that provides benefits over multiple accounting periods is generally recorded as an asset and expensed over time through depreciation, subject to applicable accounting rules.
Similarly, a payment made in advance for insurance may initially be recorded as a prepaid asset. The portion used during the accounting period is then recognized as an expense through an adjusting entry.
Students should use the chart of accounts provided with the Blue Raider Adventure Park packet. Correct classification matters just as much as entering the correct dollar amount.
Posting Transactions to the General Ledger
After journalizing transactions, the next step is posting them to the general ledger. The ledger groups all entries by account, allowing the business to calculate individual account balances.
For example, the Cash account records cash received from the owner or customers and cash paid for equipment, supplies, or other expenses. The Equipment account records qualifying equipment purchases and other applicable changes.
Posting should be completed systematically. Every debit and credit in the journal must be transferred to its corresponding ledger account, with transaction dates and references recorded when required.
The general ledger provides the information needed to prepare a trial balance. If an entry is missing from the ledger, the resulting account balances may be incorrect even when the original journal entry was recorded properly. OpenStax’s guide to journal entries and general ledger posting offers additional examples of this process.
Preparing the Unadjusted Trial Balance
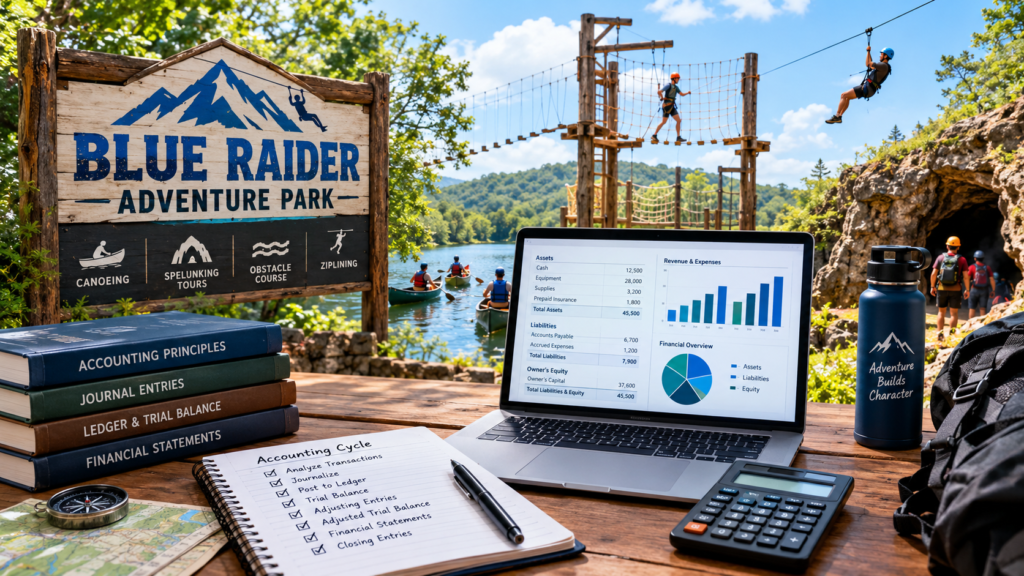
An unadjusted trial balance lists the general ledger accounts and their balances before period-end adjusting entries are recorded. Its primary purpose is to check whether total debit balances equal total credit balances.
Students should transfer each account’s ending balance into the appropriate column and calculate the totals. If the totals differ, the records need further investigation.
A balanced trial balance is an important checkpoint, but it does not prove that every transaction is correct. For example, a transaction might be completely omitted, or an incorrect account might be used while equal debit and credit amounts are still recorded.
If the trial balance does not balance, check the arithmetic first. Then trace the account balances back to the ledger and the original journal entries. Look for missing postings, transposed digits, incorrect amounts, and entries placed in the wrong column.
Adjusting Entries at September 30
The September 30 fiscal year-end is important because the business must recognize revenue and expenses in the appropriate accounting period. Adjusting entries update account balances before the adjusted trial balance and financial statements are prepared.
The original assignment determines which adjustments are required. Common examples in introductory accounting include the following.
Supplies Used
If supplies were initially recorded as an asset, the amount consumed during the period must be recognized as an expense. The adjustment depends on the original supplies balance and the amount remaining at September 30.
Depreciation on Equipment
Equipment used to operate the park may lose some of its service potential over time. Depreciation allocates the depreciable cost of a qualifying asset over its estimated useful life.
The amount depends on information such as asset cost, residual value, useful life, and the depreciation method specified or permitted by the assignment.
Prepaid Insurance
Insurance payments covering future periods may initially be recorded as prepaid insurance. At the end of the reporting period, the portion that has expired is recognized as insurance expense.
Accrued Expenses and Revenue
An accrued expense arises when a business has incurred an expense but has not yet paid or recorded it. Accrued revenue arises when revenue has been earned but has not yet been received or recorded.
These adjustments help ensure that financial statements reflect the activity belonging to the reporting period. Students should not assume that every example applies to Blue Raider Adventure Park without checking the assignment’s supporting information.
Preparing the Adjusted Trial Balance
Once all required adjusting entries have been journalized and posted, students prepare the adjusted trial balance. This report includes the updated balances of the ledger accounts after the adjustments.
The same balancing rule applies: total debits must equal total credits. If the figures do not agree, review the adjustments and ledger balances before proceeding.
The adjusted trial balance is particularly important because it provides the account balances used to prepare the financial statements. Errors at this stage can affect reported profit, assets, liabilities, and owner’s equity.
Financial Statements for Blue Raider Adventure Park
Financial statements summarize the financial results and position of a business. Depending on the instructor’s requirements, the assignment may involve preparing the following reports.
Income Statement
The income statement summarizes revenue and expenses for the reporting period. It helps determine whether the business earned a profit or incurred a loss.
If revenue exceeds expenses, the business reports net income. If expenses exceed revenue, it reports a net loss. The actual result for Blue Raider Adventure Park cannot be calculated without the assignment’s transaction figures and adjustments.
Statement of Owner’s Equity
This statement explains how owner’s equity changes during the accounting period. For a sole proprietorship, the calculation generally includes the beginning capital balance, additional investments, net income or loss, and withdrawals.
A net loss reduces owner’s equity, while additional owner investments generally increase it.
Balance Sheet
The balance sheet presents the business’s assets, liabilities, and owner’s equity at a specific date, such as September 30.
Its fundamental requirement is that total assets equal total liabilities plus owner’s equity. This statement helps readers understand what the business owns, what it owes, and the owner’s remaining interest.
Statement of Cash Flows
If required, the statement of cash flows explains cash movements through operating, investing, and financing activities. It differs from the income statement because accounting profit and cash movement are not necessarily the same.
For example, purchasing long-term equipment requires cash but is generally recorded as an asset rather than an immediate full expense. Depreciation reduces accounting profit but does not itself require a current cash payment.
Closing Entries and the Post-Closing Trial Balance
After preparing the financial statements, the accounting cycle continues with closing entries. These entries transfer temporary account balances, such as revenue, expenses, and owner withdrawals, into the appropriate owner’s equity account.
The purpose is to reset temporary accounts for the next accounting period. Permanent accounts, including assets, liabilities, and owner’s capital, continue into the following period.
The post-closing trial balance then lists the remaining permanent accounts and checks whether total debits equal total credits. Reversing entries may also be used at the beginning of the next period when appropriate, although this step is optional.
Common Mistakes Students Should Avoid
When completing the Blue Raider Adventure Park accounting assignment, pay attention to these frequent problems:
-
Incorrect debit and credit entries: Determine the account type before deciding which side increases or decreases.
-
Missing transactions: Check every transaction against the original packet and confirm that it has been recorded and posted.
-
Incorrect account titles: Use the chart of accounts supplied with the assignment rather than inventing new account names.
-
Misclassified purchases: Distinguish long-term assets from ordinary expenses and prepaid items.
-
Incomplete adjustments: Record only the adjustments supported by the assignment’s information.
-
Preparing statements too early: Complete the adjusting entries and adjusted trial balance first when the prescribed process requires them.
-
Assuming balanced totals guarantee accuracy: Check the underlying transactions because some errors do not cause a trial balance difference.
A simple checklist can make the work easier to manage. Verify the journal entries, confirm that each entry has been posted, check the trial balance, review the adjusting entries, and reconcile the adjusted balances before preparing the reports.
| 🔗 You may also like: |
| Guru Knowledge Base Software |
| Target Company URL Research: Business Analysis |
How to Complete the Assignment More Efficiently
Start by reading the entire packet and identifying every required deliverable. Keep the transaction list and chart of accounts available while working so you can verify dates, amounts, and account names.
Complete the accounting stages in sequence rather than preparing the financial statements first. If a balance is incorrect, trace it backward through the ledger and journal until you locate the source of the error.
A spreadsheet can help with arithmetic and balancing totals, provided it is permitted by the instructor. However, formulas cannot reliably determine whether a transaction has been classified correctly or whether an adjustment is justified.
For broader background, this explains the underlying system of recording equal debits and credits.
Most importantly, treat generic examples as learning aids rather than exact answers to the Blue Raider Adventure Park packet. The supplied assignment version and your instructor’s instructions determine the required figures, account names, and final reports.
Conclusion
Blue Raider Adventure Park accounting provides a practical way to understand how business transactions move through the accounting cycle. The fictional business scenario connects transaction analysis, journalizing, ledger posting, trial balances, adjusting entries, and financial statements into one continuous process.
The most effective approach is to complete each stage carefully and verify the results before moving forward. Understanding why each entry is recorded is more valuable than memorizing individual debit and credit combinations.
By following the accounting cycle in order and using the original assignment packet for exact figures, students can develop a stronger understanding of financial accounting and learn how reliable records support informed business decisions.
FAQs
What is Blue Raider Adventure Park accounting?
It is an accounting case study associated with an ACTG 2110 Principles of Accounting I assignment at Middle Tennessee State University. It uses a fictional adventure park to teach the accounting cycle.
Is Blue Raider Adventure Park a real business?
The supplied assignment pages present it as a fictional educational business scenario. They do not establish that it operates as a real commercial attraction.
What accounting course is associated with the case?
The supplied packet identifies ACTG 2110, Principles of Accounting I, and states that the serial problem covers Chapters 2–4 for Spring 2020.
What is the fiscal year-end in the case study?
The supplied introduction identifies September 30 as the fiscal year-end. The park opens to the public on September 1, following development that begins in August.
How can I calculate the exact answers?
Use the original transaction list, chart of accounts, adjustment information, and assignment instructions. Without those figures, it is possible to explain the accounting methods but not to calculate the case’s exact financial results.
What should I do if the trial balance does not balance?
Recheck the column totals, trace each ledger balance to its journal entries, and look for omitted postings, transposed numbers, incorrect amounts, or entries placed in the wrong column.